A Monetary Shift Is Building That Most Savers Will Miss 
Grounded at 52-Week Lows: When Will Boeing Stock Take Flight?
Written by Jeffrey Neal Johnson on November 19, 2026
Key Points
- Boeing has secured key FAA certifications and built a $745 billion backlog, but its stock remains near 52-week lows.
- Manufacturing constraints and slower aircraft deliveries continue to pressure Boeing's inventory levels and cash flow recovery.
- Boeing directors recently purchased approximately $1.51 million in shares as investors await more consistent production.
- Special Report: A little-known law has been quietly applied to your savings for years.

The Boeing Company (NYSE: BA) recently cleared several heavy operational overhangs. Regulators fully certified the 737 MAX family, including the anticipated 737-10 model. Boeing's engineering employees ratified four-year labor contracts, averting a potential strike. The order backlog expanded to $745 billion, bolstered by fresh widebody demand. Despite these structural victories, Boeing shares trade near 52-week lows in the $160-$170 range, roughly 16% below Wall Street's most pessimistic price target of $195.
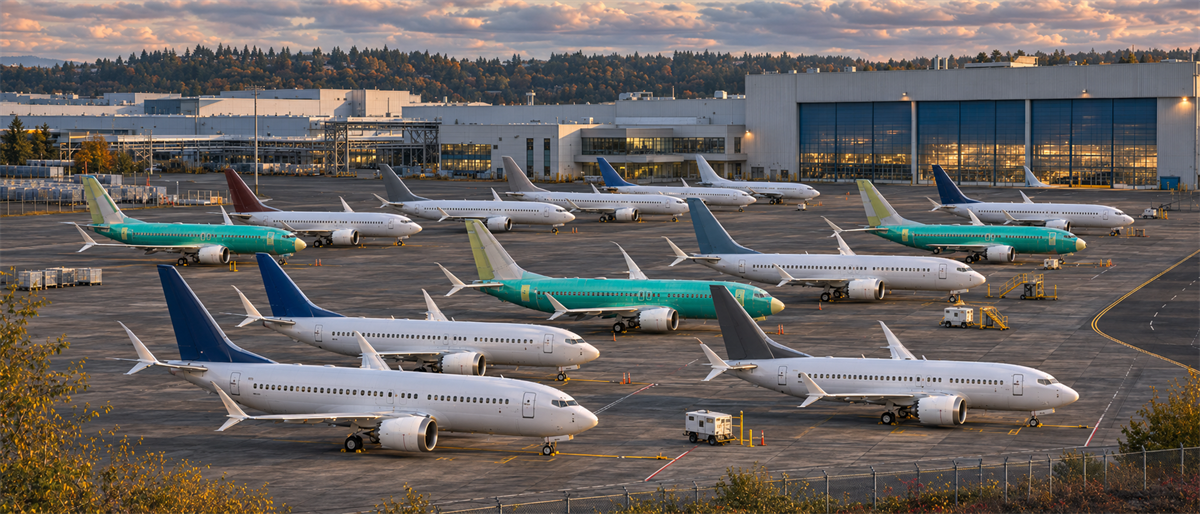
Investors are no longer waiting for orders or regulatory approvals. They are waiting for airplanes to leave the factory. With significant capital tied up in unfinished jets, Boeing's true narrative is supply chain stabilization and its ability to turn stored metal into predictable cash flow.
The ultra-wealthy have held gold for generations when the economy looks uncertain, rather than keeping every dollar in stocks and bonds.
Warning signs include a national debt Elon Musk has called out, a Washington spending fight, and the risk of higher borrowing costs and market swings hitting retirement accounts. Physical gold can be held inside an eligible retirement account.
Gold has seen a historic price surge, and the free guide covers what financial experts are forecasting next.
Get your free Warning Gold Guide from Reagan Gold Group today.
Holding Pattern: Strong Demand Meets Factory Friction
At first glance, the fundamentals appear misaligned with the stock chart. The Federal Aviation Administration cleared Boeing to increase 737 production toward 47 aircraft per month and restored its authority to issue airworthiness certificates for 737 MAX and 787 aircraft under FAA oversight. On the commercial front, airlines continue to line up. Allegiant Travel Company (NASDAQ: ALGT) exercised options for six additional 737-8 MAX aircraft, lifting its firm commitments to 56 jets, while international carriers finalize billion-dollar agreements.
Strong demand only supports a stock price if a business can physically execute. The core friction keeping prices suppressed stems from manufacturing bottlenecks, particularly in the Renton wing back shops and broader supply chain. These constraints pushed the timeline for a steady 47-per-month 737 production rate into 2027.
October deliveries slipped to 49 total aircraft, with only 32 being 737 MAXs. Aircraft delivery delays are also benefiting aerospace service providers as airlines extend the service lives of existing fleets. When factory throughput stalls, record order announcements lose their ability to support the stock's value. Markets discount the timeline of future cash flows, waiting for upstream suppliers to catch up to assembly capacity. Until delivery numbers accelerate, the top-line demand metrics carry less weight in daily trading decisions.
Dropping Excess Weight to Repair the Balance Sheet
Valuing an aerospace manufacturer in the middle of a turnaround requires looking past surface-level metrics. A casual stock screen shows a trailing price-to-earnings ratio near 17.8x, but that figure is skewed by a non-recurring $9.6 billion pre-tax gain from the late-2025 divestiture of the digital aviation business. Stripping away one-time asset sales, Boeing still reported a core loss per share in the third quarter, while forward earnings multiples remain elevated and vary by estimate source.
A more accurate lens for this phase of the business cycle is the price-to-sales multiple. Shares currently trade at roughly 1.4x trailing annual sales. For context, primary competitor Airbus SE (OTC: EADSY) trades closer to 2x sales. This discount reflects the ongoing margin compression within the commercial airplanes division and a delayed cash flow profile.
Leadership is actively taking steps to streamline operations and repair the balance sheet. Consolidated debt rests around $45.9 billion, and The Boeing Company is nearing a stock-and-warrant transaction involving the sale of three autonomy-focused subsidiaries to Archer Aviation Inc. (NYSE: ACHR). This planned divestiture of Wisk, SkyGrid, and Insitu trims research and development cash burn while allowing the enterprise to retain a strategic equity stake. Analysts remain cautious. Morgan Stanley lowered its price target to $195, though even that pessimistic view sits comfortably above current trading levels.
The U.S. national debt just topped $39 trillion, up nearly $3 trillion in a single year and on pace to hit $40 trillion by year end.
Servicing that debt now costs more than the entire defense budget, while inflation above 3.5% keeps eroding cash savings. Central banks are responding by buying gold at the fastest pace in decades.
The U.S. Gold Bureau's complimentary guide covers IRA-eligible gold and silver options, secure storage, and a fast BuyBack Guarantee.
Claim your complimentary Gold IRA guide today
Factory Resets and Digital Tracking Take Flight
The most compelling data point is found deep within Boeing's balance sheet. Total inventory recently reached about $90.9 billion, reflecting a substantial amount of capital tied up in aircraft production. As of Sept. 30, this figure included about 45 prebuilt 737-7 and 737-10 aircraft awaiting final customer handover.
This inventory stockpile creates a sharp divergence in liquidity metrics. The current ratio looks relatively healthy at 1.13, but the quick ratio drops to a tight 0.34 when removing difficult-to-liquidate inventory. The primary opportunity is converting this stored work-in-process into working capital. Delivering completed jets can release working capital and generate cash that can pay down debt and fund future development.
To align fixed costs with actual factory pacing, leadership announced plans to reduce the commercial workforce by 5%, potentially affecting roughly 2,500 positions through layoffs and attrition. While workforce reductions present internal challenges, they reflect a pragmatic reset to match production speed with engine and seat availability. The organization cannot afford to build planes faster than suppliers can provide the necessary components.
Simultaneously, The Boeing Company is addressing part verification to prevent future bottlenecks. A newly expanded digital tracking initiative with GE Aerospace (NYSE: GE) aims to tighten supply chain oversight and prevent unapproved components from entering the ecosystem. By issuing electronic airworthiness certificates, they are building the digital infrastructure needed to support a smoother, more reliable production ramp.
Boardroom Boarding Passes: Insiders Buy the Dip
Market positioning currently reflects a tug-of-war between short-term hedging and long-term accumulation. Options markets show elevated put-trading activity, with volume recently rising well above average. This may reflect demand for downside protection surrounding the fourth-quarter free cash flow hurdle, which requires generating over $2 billion to meet full-year targets.
Conversely, direct equity short interest remains low at roughly 2.2% of the float. More notably, board leadership is stepping in with personal capital. Directors Steven Mollenkopf and Mortimer Buckley executed open-market purchases totaling approximately $1.51 million near the $172 level. When the architects of a corporate turnaround begin buying shares near 52-week lows, it warrants attention from value-oriented investors.
For investors evaluating a potential entry, the roadmap depends on factory execution rather than new orders. A sustainable valuation floor will likely form once monthly 737 deliveries rebound consistently from the low 30s toward the mid-40s. The planned December increase in 787 production from eight to ten jets per month will be another key checkpoint for supply chain health.
Patient investors may want to track these monthly delivery metrics closely. As inventory begins to liquidate and working capital flows back into the business, the bridge to management's multi-billion-dollar free cash flow targets for the late 2020s will become much clearer. The pieces for a recovery are falling into place, with the assembly line dictating the pace.
Read this article online ›
Further Reading
Did you enjoy this article?
 
|


0 Response to "The Delivery Numbers That Could Unlock Boeing's Recovery"
Post a Comment