For half a century, the world's prosperity has run on oil.
And every time oil gets scarce, the whole world pays for it. Gas lines in the 1970s. Price spikes in 2008 and 2022. Inflation, shortages and slowdowns that ripple through every economy on Earth.
This week, one small company took a real step toward a different answer: energy that doesn't need oil at all.
Near Vancouver, a machine just heated plasma to an astonishing 12.6 million degrees Celsius… more than 2,000 times hotter than the surface of the sun!
The company calls it a world-first: the first fusion energy machine to cross the 1 keV threshold using its practical, industrial compression approach. Fusion energy could be our key to freeing the world's economy from the boom-and-bust cycle of oil.
No drilling. No pipelines. No oil shocks.
The company trades on the Nasdaq. Jeff Bezos was an early investor. And right now, almost everyone is too busy watching oil prices to notice. See the company that could make oil shocks.
The Investment Journal P.S. For 50 years, oil has made scarcity the world's biggest energy risk. Fusion could offer something different: abundance. [Read more here.]
All investments are subject to risk, which must be considered on an individual basis before making any investment decision. This paid advertisement includes a stock profile of General Fusion Group Ltd. (Nasdaq: GFUZ) ("General Fusion"). The Investment Journal is an investment newsletter being advertised herein. This paid advertisement is intended solely for information and educational purposes and is not to be construed under any circumstances as an offer to sell or a solicitation of an offer to purchase any securities. General Fusion funded a budget of approximately $315,600 to Creative Direct Marketing Group ("CDMG") to cover the costs associated with creating, printing and distributing this advertisement. In addition, The Investment Journal may receive subscription revenue in the future from new subscribers as a result of this advertisement for its newsletter. CDMG will retain any excess sums after all expenses are paid. While this advertisement is being disseminated and for a period of not less than 90 days thereafter, The Investment Journal, CDMG, and their respective officers, principals, or affiliates will not sell securities of General Fusion. If successful, this advertisement will increase investor and market awareness of General Fusion and its securities, which may result in an increased number of shareholders owning and trading the securities, increased trading volume, and possibly an increase in share price, which may be temporary. This advertisement, CDMG and The Investment Journal do not purport to provide a complete analysis of General Fusion or its financial position. They are not, and do not purport to be, broker-dealers or registered investment advisors. This advertisement is not, and should not be construed to be, personalized investment advice directed to or appropriate for any particular investor. Any investment should be made only after consulting a registered broker-dealer or registered investment advisor or, at a minimum, doing your own research if you do not utilize an investment professional to make decisions on what securities to buy and sell, and only after reviewing the financial statements and other pertinent publicly available information about General Fusion. Further, readers are specifically urged to read and carefully consider the risk factors identified and discussed in General Fusion's Securities and Exchange Commission ("SEC") filings. Investing in General Fusion is speculative and carries a high degree of risk. Past performance does not guarantee future results. This advertisement is based exclusively on information generally available to the public and does not contain any material, non-public information. The information on which it is based is believed to be reliable. Nevertheless, CDMG and The Investment Journal cannot guarantee the accuracy or completeness of the information and are not responsible for any errors or omissions. This advertisement contains forward-looking statements, including statements regarding expected future growth of General Fusion and/or its industry. CDMG and The Investment Journal note that statements contained herein that look forward in time, which include everything other than historical information, involve risks and uncertainties that may affect the actual results of operations of General Fusion. The Investment Journal is the publisher's trademark. All trademarks used in this advertisement other than The Investment Journal are the property of their respective trademark holders and no endorsement by such owners of the contents of this advertisement is made or implied. CDMG and The Investment Journal are not affiliated, connected, or associated with, and are not sponsored, approved, or originated by, the trademark holders unless otherwise stated. No claim is made to any rights in any third-party trademarks.
Certain statements included in this document are not historical facts but are forward-looking statements within the meaning of the U.S. federal securities laws and "forward-looking information" within the meaning of applicable Canadian securities laws (collectively, "forward-looking statements"). All statements other than statements of historical facts contained in this advertisement are forward-looking statements. Any statements that refer to projections, forecasts, or other characterizations of future events or circumstances, including any underlying assumptions, are also forward-looking statements. In some cases, you can identify forward-looking statements by words such as "estimate," "plan," "project," "forecast," "intend," "expect," "anticipate," "believe," "seek," "strategy," "future," "opportunity," "may," "target," "should," "will," "would," "will be," "will continue," "will likely result," "preliminary," or similar expressions that predict or indicate future events or trends or that are not statements of historical matters, but the absence of these words does not mean that a statement is not forward-looking. Forward-looking statements include, without limitation, statements regarding the outlook for General Fusion's business, including its ability to commercialize Magnetized Target Fusion ("MTF") or any other fusion technology on its expected timeline or at all and its ability to generate revenue; statements regarding the future price or value of General Fusion's securities, statements regarding the current and expected results of the Lawson Machine 26 ("LM26") program; as well as any information concerning possible or assumed future results of operations or financial position of General Fusion.
These forward-looking statements are provided for illustrative purposes only and are not intended to serve as, and must not be relied on as, a guarantee, an assurance, a prediction or a definitive statement of fact or probability. Actual events and circumstances are difficult or impossible to predict and will differ from assumptions, many of which are beyond the control of General Fusion. These forward-looking statements involve a number of risks, uncertainties, or other assumptions that may cause actual results or performance to be materially different from those expressed or implied by these forward-looking statements. These risks and uncertainties include, but are not limited to, the risk that General Fusion is unable to maintain the listing of its securities on Nasdaq; the risk that the price of General Fusion's securities may be volatile due to a variety of factors outside of its control, the risk that the conversion or exercise price of General Fusion's PIPE warrants and convertible preferred shares may be reduced substantially in accordance with the terms thereof resulting in material dilution, the risk that price of General Fusion's shares is negatively affected by the release of approximately 41 million subordinate voting shares from a lock-up in January 2027 (unless released earlier), the risk that General Fusion never generates revenue; the risk that General Fusion fails to commercialize MTF on a cost-effective basis, on the expected timeline or at all; the risk that General Fusion fails to achieve the objectives of the LM26 program; the risk that additional capital needed by General Fusion may not be raised on favorable terms, or at all, including as a result of the restrictions agreed to in connection with the PIPE financing General Fusion closed on July 10, 2026; the risk that fusion energy does not gain public acceptance; the risk that the scientific and technical assumptions upon which MTF technology is based do not prove to be correct; the risk that General Fusion's competitors develop viable fusion technology sooner than it does; the risk of supply chain disruptions; the risk that key technical material and service inputs may not be available when required on reasonable terms or at all; the risk that General Fusion is unable to attract and retain qualified personnel with highly technical expertise; the risk that General Fusion is subject to negative publicity; the risk that General Fusion's assessment of the total addressable market for fusion energy is incorrect; the risk of changes in the laws and regulations governing General Fusion's research and development activities and in the regulation of fusion energy; the risk of fluctuations in currency markets; the risk that General Fusion is unable to complete and successfully integrate any future acquisitions; the risk of increased competition in the fusion industry; the risk of accidents, earthquakes, fires, floods and other natural disasters; the risk that General Fusion's information technology fails; the risk that General Fusion's operating expenses are materially higher than forecast; the risk that General Fusion is unable to remediate material weaknesses in its internal controls or identify additional material weaknesses in the future; the risk that General Fusion is unable to adequately protect or enforce its intellectual property rights; the risk of third-party claims that General Fusion is infringing or violating another person's intellectual property rights; the risk that General Fusion's intellectual property applications are not granted; the risk of a cyber event or privacy breach resulting in an interruption in operations or financial loss; the risk that the Canadian government reduces or delays funding of government programs in which General Fusion participates; the risk that future sales by existing shareholders could cause General Fusion's stock price to decline; and the risk that General Fusion is unable to establish and maintain effective internal controls to produce accurate and timely public disclosure.
These forward-looking statements are based on certain assumptions, including that none of the risks identified above materialize; that there are no unforeseen changes to economic and market conditions, and that no significant events occur outside the ordinary course of business.
The foregoing list is not exhaustive, and there may be additional risks that are not known or are currently believed to be immaterial. You should carefully consider the foregoing factors, any other factors discussed herein and in the other filings by General Fusion with the SEC, including those described under the heading "Risk Factors." Neither General Fusion nor any other party undertakes to update any forward-looking statements, whether as a result of new information, future events, or otherwise, except as required in accordance with applicable laws.
Cautionary Note Regarding Technical Results and Forward-Looking Statements
References to plasma heating results, electron temperatures, and technical milestones are based on General Fusion's own disclosures, including results the company has stated are submitted for peer review. Such results are preliminary in nature and do not guarantee the achievement of subsequent milestones, including the 1 keV or 10 keV heating targets or the Lawson criterion. Commercialization of fusion energy remains subject to substantial scientific, engineering, regulatory, and financial risk.
This message is a PAID ADVERTISEMENT for General Fusion Group Ltd. (Nasdaq: GFUZ) from Creative Direct Marketing Group, Inc. StockEarnings, Inc. has received a fixed fee of Fifteen Thousand USD from Creative Direct Marketing Group, Inc for multiple Dedicated Email Sends, Newsletter Sponsorships and SMS Sends between Oct 9 2026 12:00AM and Oct 14 2026 12:00AM. Other than the compensation received for this advertisement sent to subscribers, StockEarnings and its principals are not affiliated with either General Fusion Group Ltd. (Nasdaq: GFUZ) or Creative Direct Marketing Group, Inc. StockEarnings and its principals do not own any of the stocks mentioned in this email or in the article that this email links to. Neither StockEarnings nor its principals are FINRA-registered broker-dealers or investment advisers. The content of this email should not be taken as advice, an endorsement, or a recommendation from StockEarnings to buy or sell any security. StockEarnings has not evaluated the accuracy of any claims made in this advertisement. StockEarnings recommends that investors do their own independent research and consult with a qualified investment professional before buying or selling any security. Investing is inherently risky. Past-performance is not indicative of future results. Please see the disclaimer regarding General Fusion Group Ltd. (Nasdaq: GFUZ) on theinvestmentjournal website for additional information about the relationship between Creative Direct Marketing Group, Inc and General Fusion Group Ltd. (Nasdaq: GFUZ).
Today’s editorial pick for you
September Earnings Recap: 3 Stocks With Results Worth Buying
Posted On Oct 05, 2026 by Grayson Cavern
Some earnings reports answer questions investors have been asking for months. Others create entirely new ones. September gave us both, with Adobe (NASDAQ: ADBE), Casey’s General Stores (NASDAQ: CASY), and Oracle (NYSE: ORCL) delivering results that deserve a closer look beyond their headline revenue and EPS figures.
Table of Contents
I had already examined the questions surrounding these three businesses before or around their earnings releases: whether Adobe could turn AI adoption into actual revenue, whether Casey’s slowing same-store sales concealed stronger underlying profitability, and whether Oracle could convert its enormous AI backlog into financial performance. Their latest results provide new evidence for each argument, although the conclusions aren’t equally straightforward.
If you put $24,000 into Newmont, one of the biggest mining stocks out there, you could collect about $240 a year. That's a 1% yield for one year of waiting for a payout that barely covers groceries.
Now here's the same $24,000 in a different investment…
A little-known $15 fund tied to gold that could pay $1,127 in just 30 days. Nearly 5X the income…
And with 28 times less capital to get there compared to a regular dividend stock.
This is the difference between owning gold and getting paid from gold every Friday.
Adobe Stock Shows AI Growth Is Turning Into Revenue
In my previous coverage of Adobe, I questioned whether the company’s growing AI audience could translate into meaningful revenue. Its Q3 FY2026 report gave us a much clearer answer, with AI-first ARR surpassing $650 million, up more than 150% year over year.
The company also delivered $6.76 billion in revenue, representing 13% growth, while non-GAAP EPS climbed 15% to $6.13. Both figures exceeded expectations, and management raised its full-year revenue and earnings outlook.
Firefly’s ending ARR grew 40% sequentially, providing another indication that customers are beginning to pay for Adobe’s AI capabilities. More importantly, Adobe is taking these tools into its enterprise ecosystem, where businesses already spend heavily on content creation, marketing and customer experience.
That gives the company a sizeable installed base from which to expand AI monetization, although its total ARR growth slowed to 11.2% from 12.5% in Q2. Yes, the AI business is growing rapidly, but the company still needs to prove it can accelerate its broader revenue base.
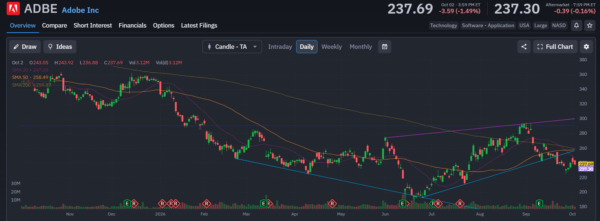
ADBE closed October 2 at $237.69, trading below its 20-day SMA at $247.05, 50-day at $258.49, and 200-day at $259.87. The chart has deteriorated considerably from its September peak near $295, with the stock now testing the lower end of its recent trading range.
I want to see buyers reclaim $247 first, followed by the 258–260 cluster where the 50-day and 200-day averages converge. That would provide the first meaningful evidence of a trend reversal. Until then, the earnings strength makes ADBE attractive to me, but the chart still needs repairing.
When Casey’s reported its first-quarter results, the market punished the stock for slowing same-store sales despite a 27.7% increase in diluted EPS. I once made a case that the headline sales figures weren’t telling the entire story, particularly as fuel margins expanded and the company continued adding stores.
The September report reinforced the importance of looking beyond that comparable-store growth. Revenue reached $5.68 billion, up 24.3%, while diluted EPS increased to $7.37 from $5.77 a year earlier. Net income rose to $273.7 million, and EBITDA advanced 17.1% to $485.1 million.
The margin story deserves some attention as well, as fuel gross profit climbed 19.6% to $446.9 million even as same-store fuel gallons declined 0.3%. Inside gross profit also increased 6.3%, supported by prepared food and dispensed beverages. Casey’s is extracting more profit from its existing operations while expanding its footprint. Management expects at least 120 new stores through acquisitions and construction in fiscal 2027, giving the company another avenue for growth.
There are risks. Operating expenses increased 8%, and fuel margins can fluctuate. Still, the earnings performance gives me confidence that the company has more going for it than its comparable-store sales figures suggest.
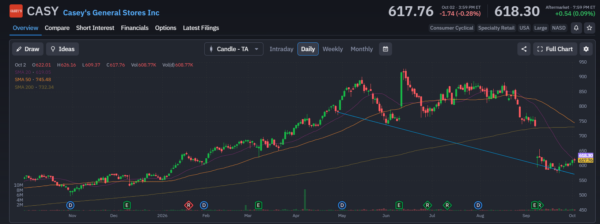
The stock closed October 2 at $617.76, hovering around its 20-day SMA at $619.05 after recovering from the $590 area. That recovery is encouraging, although the stock remains well below its 50-day average at $745.48 and 200-day at $732.34.
The $600 region is the immediate support zone I want buyers to defend. A sustained move above $620 would improve the short-term setup, while reclaiming 732–745 would mark a much stronger recovery. I am buying CASY here, with the understanding that the chart has yet to confirm a broader trend reversal.
Oracle Stock Surges on Cloud Growth and a $664 Billion Backlog
Ahead of Oracle’s September earnings report, I argued that its $638 billion backlog was only half the story. The bigger question was whether the company could convert those commitments into revenue without allowing infrastructure spending to overwhelm its financial position.
Q1 FY2027 delivered a significant step forward on the demand side. Revenue increased 30% to $14.93 billion, while cloud revenue surged 62% to $11.67 billion. Cloud infrastructure revenue was particularly impressive, climbing 121% to $4.21 billion.
Remaining performance obligations also increased to $664 billion from $638 billion in June. That is another $26 billion in contracted future business, reinforcing the scale of demand Oracle is attracting.
However, capital expenditure reached $28.5 billion, leaving free cash flow negative $5.4 billion. Oracle is now converting customer demand into substantial revenue growth, but the cost of building the capacity to service those commitments remains enormous.
I want to see how quickly that spending translates into stronger cash economics. For now, the demand trajectory is strong enough to keep me bullish.
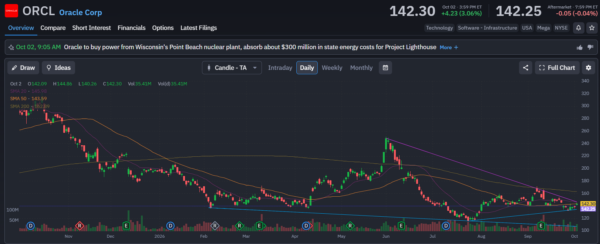
ORCL closed October 2 at $142.30, below its 20-day SMA at $145.98, 50-day at $143.59 and 200-day at $162.89. The chart is compressing around the 140–145 region, with a descending resistance trendline limiting upside.
A break above $146 would be the first sign of improving momentum, while $150 represents another area worth watching. Reclaiming the 200-day average near $163 would provide a much stronger technical confirmation.
I am buying ORCL because its cloud growth and expanding backlog give the company a substantial revenue opportunity, even as investors demand evidence that the infrastructure spending will eventually pay off.
Today’s editorial pick for you
5 Stocks Goldman Sachs Sees Gaining Ground Ahead of Earnings
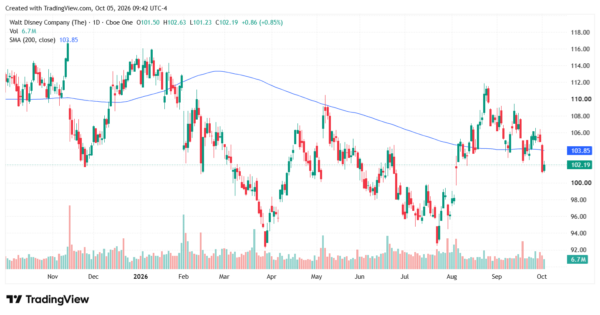
Disney Stock Offers a Long-Term Earnings Growth Story
Disney remains a favorite of Goldman analyst Michael Ng, who sees several years of earnings growth ahead. His argument reaches across Disney’s businesses, including theme parks, entertainment, and sports. Goldman believes the company is still early in an investment cycle that could strengthen its offerings and support future profits.
Ng estimates earnings per share could grow at a compound annual rate of roughly 13% over the period covered by his outlook. That means he expects earnings to build on themselves over time, although growth won’t necessarily follow a straight line. He lowered his price target to $140 from $144 but maintained his positive stance.
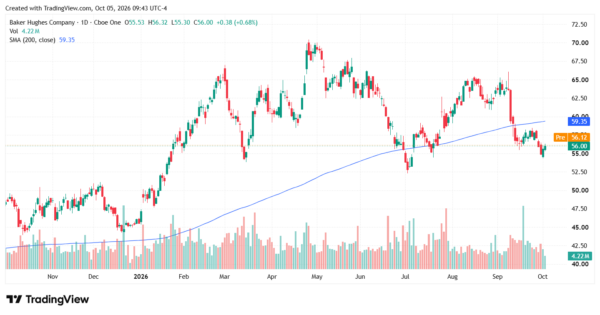
Baker Hughes Stock Could Benefit From Its Chart Industries Deal
With Baker Hughes, Goldman analyst Neil Mehta reinstated coverage with a Buy rating following the company’s acquisition of Chart Industries. He sees opportunities for the combined business to increase revenue and improve profit margins.
The reasoning is straightforward. Combining operations could reduce overlapping expenses, while a broader geographic reach could help the company sell more products and services to more customers. Goldman sees several ways for earnings to expand through 2030, suggesting its investment case extends well beyond the next quarterly report.
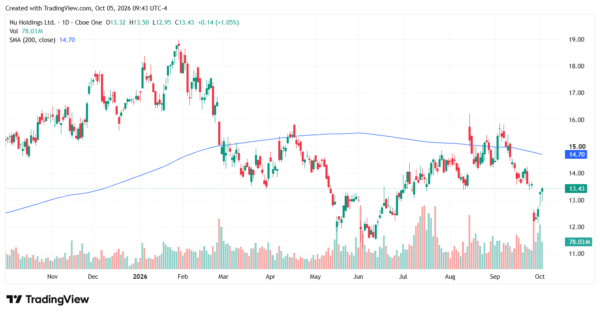
Nu Stock Has Room to Expand in U.S. Consumer Lending
Nu Holdings has attracted Goldman’s attention for its potential expansion into U.S. consumer lending. Analyst Tito Labarta believes the Latin American financial technology company’s digital approach could help it compete. The appeal centers on keeping operating costs low while making financial services convenient for customers. Goldman also points to Nu’s ability to expand without allowing expenses to rise at the same pace.
That combination could be valuable in a new market, although the U.S. lending business is highly competitive. Winning customers is only part of the challenge. Nu would also need to manage lending risks and expansion costs.
Labarta maintained a Buy rating and a $23 price target. Notably, Goldman’s estimates include some initial U.S. expansion expenses without incorporating the potential upside.
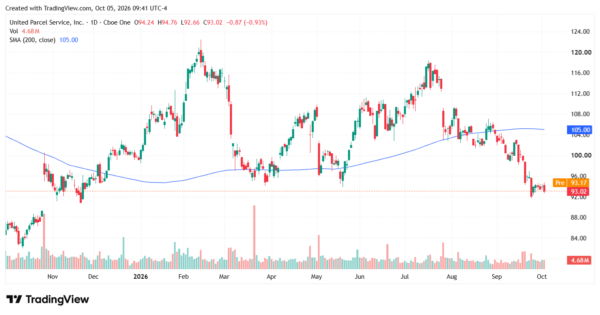
UPS Stock Could Gain as Cost Cuts Improve Profitability
UPS has been reducing Amazon package volume and adjusting its costs accordingly. That transition can weigh on results while the business reshapes its delivery network. Goldman believes profit growth could become more consistent as that process concludes. The bank expects a leaner domestic operation, greater automation, and a more profitable mix of shipments to improve the business.
The important distinction is that package volume and profitability don’t always move together. Delivering more packages isn’t necessarily better if those shipments generate limited profit.
Investors will want evidence that cost reductions are keeping pace with volume changes and that the remaining business can produce stronger returns.
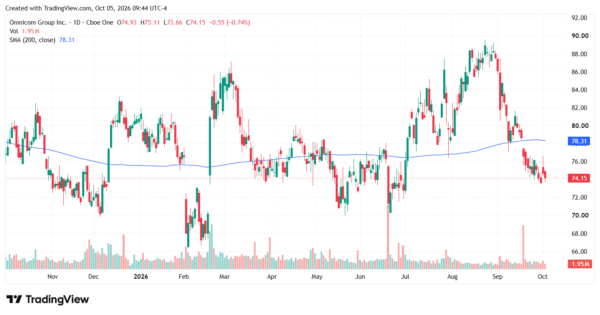
Omnicom Stock Could Benefit From Stronger Advertising Growth
Goldman believes Wall Street may be underestimating Omnicom’s underlying revenue growth.
Its optimism centers on the advertising company’s media business, where it expects continued double-digit growth. The bank also highlighted a valuation of roughly six times estimated 2027 earnings in its cited analysis. That could attract investors if upcoming results support its growth expectations.
These Five Stocks Have Earnings Catalysts to Watch
These five stocks offer different paths to stronger earnings. Disney is investing in its businesses, Baker Hughes is looking to benefit from an acquisition, and Nu has opportunities to reach new customers. Meanwhile, UPS is working to improve profitability, and Omnicom could benefit if its growth proves stronger than Wall Street expects.
What makes this group interesting is that each company has something specific investors can watch. Are investments translating into higher profits? Are cost cuts improving margins? Is expansion bringing in enough business to justify the expense? The upcoming earnings reports should help show how much progress these companies are making.
Of course, a Buy rating from Goldman Sachs doesn’t guarantee a stock will rise. Expectations matter, too, and even a solid quarter can disappoint investors who were looking for more. That’s why management’s outlook deserves just as much attention as the headline earnings numbers.
For investors building a watchlist, these five names provide a useful starting point. The next step is to see whether their results—and the price investors are being asked to pay—support the optimism.



0 Response to "Why $100 oil might matter less to investors after this week"
Post a Comment