Welcome to Insider Trades Daily. We’re glad you’re here! More than 500,000 investors use this newsletter to keep track of insider buying and selling across publicly traded companies. Why? Because it gives you a simple way to see what the people closest to a company are doing with their own shares. Before we send your first issue, there’s just one quick step left: Click Here to Confirm Your Subscription to Insider Trades Daily It takes a few seconds and helps make sure your newsletter shows up where it belongs, your inbox, not a spam folder. Once confirmed, you’ll start receiving clear, no-nonsense coverage of insider purchases, insider sales, notable transactions, and other activity worth having on your radar. We’ll do the digging. You’ll get the highlights delivered straight to your inbox. Start Receiving Insider Information The InsiderTrades.com Team P.S. Your first issue can’t be delivered until your subscription is confirmed. Confirm your email here and we’ll take it from there.
Additional Reading from MarketBeat Media
ASML Can’t Keep Up With AI Demand—Why That's a Good ThingAuthored by Thomas Hughes. Date Posted: 10/15/2026. 
Key Points
- ASML's CEO said demand will exceed supply through 2028, even after planned 30% capacity increases over the next two years.
- The company posted mixed Q3 revenue but stronger margins, raised full-year guidance and issued a strong forecast for the fourth quarter.
- Analysts maintain a consensus Moderate Buy rating with roughly 25% upside, while technical charts and capital returns point to further gains.
- Special Report: The Untouched Energy Source Behind a New Eight Year Tax Break
ASML (NASDAQ: ASML) sent two strong signals in its Q3 report: one company-specific and the other related to the broader AI industry. The company-specific signal is that demand is high—so high, in fact, that planned capacity increases of 30% over the next two years will not be enough to meet it. According to CEO Christophe Fouquet, demand will exceed supply through 2028, pushing the company to make critical decisions, including ramping production and expanding its plans for new capacity. Industry signals are also robust.
China controls more than 90% of global rare earth alloy production, leverage it is using to restrict exports to the U.S.
With a January 1, 2027 deadline approaching, the Pentagon selected four companies to build critical mineral processing facilities on U.S. military bases. Only one was chosen for heavy rare earths - a Nasdaq-listed firm with an Ohio metallurgy facility under Pentagon contracts and rights to 80% of output from a major Canadian processing plant. See why this rare earth stock deserves a closer look today
The industry-specific signal is that demand remains strong across computing and memory, with supply constraints likely to persist through 2028, if not longer. More importantly, customers are already interested in products planned for 2029 and 2030, underscoring the timing and intensity of AI demand—both of which the broader market still underestimates. These signals translated into solid results and improved guidance for ASML, with trends suggesting not only continued strength but also outperformance and potential acceleration in the coming quarters. ASML’s Mixed Quarter Overshadowed by Demand Signals and GuidanceASML reported a mixed quarter, with Q3 revenue falling slightly short of consensus estimates. However, the bar was high: Nearly 100% of earnings forecasts had been raised since the last report, pricing in an immediate production ramp despite how unlikely that was to occur. Third-quarter sales were supported by new and used machines, as well as services for the installed base. Installed-base revenue grew 19%, new-unit sales increased 31.3%, and used-unit sales rose marginally. Margin news was even better than the revenue results. Gross margin widened as increased leverage and stronger sales flowed through the report to the bottom line. Although investments weighed on cash flow, the impact was minimal and left the company’s financial position strengthened. Adjusted earnings per share outperformed by 2,000 basis points, aided by a one-time gain, but still exceeded expectations when excluding that gain. Guidance sets the stage for future catalysts. The company raised the low end of its full-year guidance, issued a strong forecast for Q4 and will likely perform at the high end of the range, if not outperform it. Catalysts include next year’s guidance, which will reflect ASML’s planned 30% increase in chipmaking equipment production capacity in 2027, as well as any additional capacity expansions the company announces. ASML’s Dividends, Buybacks and Bullish Signals Point to More UpsideAmong ASML’s attractions are its capital returns. The company pays dividends, buys back shares and could accelerate both programs in the coming year. The interim dividend is tracking the company’s long-term trend, with 10 years of steady, double-digit increases and a payout ratio near 20%. Share buybacks offset share-based compensation and incrementally reduce the share count, boosting per-share earnings growth and investor leverage. Analysts expressed some concern about the capacity constraint, noting that it could hinder growth, but they remain otherwise bullish on the stock. The 27 analysts tracked by MarketBeat reflect strong conviction in the consensus Moderate Buy rating and price target, which indicated approximately 25% upside as of mid-October. The trend is important, with price targets rising ahead of the release. High-end price targets suggest a move to the $2,600 range within 12 months, representing approximately 50% upside. Technical signals are equally bullish. The market was consolidating as of mid-Q4 but remained within an uptrend, suggesting higher levels ahead. Support appears strong near $1,600, while the MACD shows a head-and-shoulders reversal pattern, leaving the market positioned for a potential move higher. 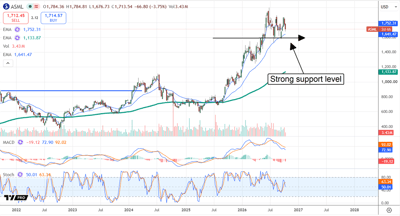
Critical resistance sits near the existing highs and could trigger capital inflows if broken. Assuming new highs are set, the patterns in place—including the consolidation and preceding rally—suggest that a $500 to $600 move could follow, enough to match the analysts’ high-end target range. Don’t Mistake the Size and Depth of ASML’s MoatInvestors should not mistake ASML’s supply constraint for a weakness. The company has a deep moat as the only supplier of extreme ultraviolet lithography machines, which are essential for producing the most advanced AI-capable chips. ASML cannot lose demand; it can only defer that demand until it has the capacity to meet it. The question now is whether a capacity ramp is really necessary, since oversupplying the market could have far-reaching, long-lasting repercussions. If ASML does not ramp capacity, its revenue and earnings visibility could extend well into the next decade. ASML’s biggest risk is disruption. Another company could develop a semiconductor-printing machine superior to its products. However, that risk appears slim, as there are no direct competitors today and emerging technologies remain far from practical application. In this scenario, ASML is an execution story that needs only to meet demand at a steady pace, control costs and generate cash flow and capital returns for its stock price to continue moving higher.
(ARReply-193) |


0 Response to "Follow the money"
Post a Comment