Good morning! I noticed your MarketBeat signup never quite got finished. We’re still waiting for you to confirm penunggangbadai.moneyblog@blogger.com. If that’s your email address and you want to keep hearing from us, just click below: Yes, "penunggangbadai.moneyblog@blogger.com" is my correct email address. Thank you, and talk soon!
Laycee Kluin
MarketBeat
P.S. Need help with anything regarding your account? Just hit reply or send a new email to us at contact@marketbeat.com. We're always here to help!
This Week's Bonus Story
3 Stocks Chopped in Half: Why These Drops May Be Structural, Not a DipAuthor: Dan Schmidt. Article Posted: 10/11/2026. 
Key Points
- lululemon, The Trade Desk, and Charter Communications have each seen their stock prices fall more than 50% due to structural business declines, not temporary setbacks.
- lululemon faces an 8% drop in North American comparable sales as it loses market share to premium athleisure rivals like Alo Yoga, with no quick turnaround in sight.
- Trade Desk's revenue growth has stalled to just 3% with guidance now projecting its first-ever year-over-year sales decline, while Charter continues losing broadband subscribers and revenue per user.
- Special Report: The Last Energy Revolution Starts Now
When you see a popular brand's stock down 50%, you may feel a deep-seated urge to buy the dip. Ubiquitous companies don’t just fade away; a rebound is on the horizon, and the stock is probably cheap, right? Well, you might want to check with Nike Inc. (NYSE: NKE) investors before assuming that what goes down must also go back up. The wheels of capitalism never stop turning, and newer, leaner competitors often send formerly successful businesses to the trash bin. And yes, sometimes even your favorite brands are affected. Not long ago, lululemon athletica (NASDAQ: LULU) was a premium athleisure brand, The Trade Desk Inc. (NASDAQ: TTD) was a leading ad-buying platform, and Charter Communications Inc. (NASDAQ: CHTR) was one of the largest broadband operators in the U.S. But now, all three stocks have fallen at least 50%, and it's not because of a bad quarter or a temporary macroeconomic scare. Each company faces a structural decline, and the evidence keeps piling up quarter after quarter. Here’s why they’re losing market share and what might have to happen for the stocks to bottom. lululemon: High-End Brand Losing Its Premium
Docket No. OP-1670 is drawing attention for what it reveals about the Federal Reserve's next move. Buried on page 84 is a plan that could expand oversight of checking accounts, purchases, and money transfers across the country.
Martin D. Weiss, PhD, founder of Weiss Ratings, breaks down what this document means and why it could roll out as soon as this summer. Watch the video to learn how this plan could affect you
lululemon’s struggles are well documented, and the fiscal Q2 2026 report on Sept. 3 offered no relief to weary investors. Revenue fell 4.3% year over year (YOY), and management again lowered its sales guidance by 5% to 7%. Earnings per share (EPS) beat expectations, but 86 cents per share of the earnings beat came from one-time tariff refunds, which inflated the number well above consensus. But the alarming metric is North American comparable sales, which declined 8% YOY. The Americas are lululemon’s largest market, and continued declines here point to a problem with its core customer base. The company is losing market share to premium athleisure brands like Alo Yoga, and other major athletic apparel companies aren’t seeing as steep a decline in revenue and comparable sales. Falling comparable sales and guidance cuts mean earnings will likely continue moving in the wrong direction, and there won’t be a tariff refund in Q3 to buoy the results. 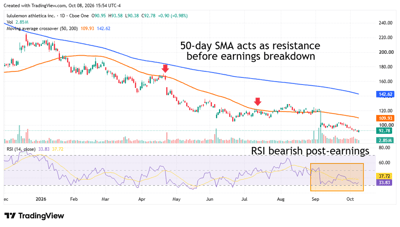
The stock plummeted 18% after the earnings release, adding evidence that the 50-day moving average has become the new primary resistance level. LULU's year-to-date (YTD) drop has now reached 55%, and the relative strength index (RSI) still hasn’t dipped below the oversold threshold of 30. It will be tough to call a bottom in LULU until American comparable sales improve and the company stops cutting guidance. Trade Desk: The Growth Story Is OverTrade Desk shares have sunk faster than the Philadelphia Eagles' playoff chances. The stock is down more than 65% YTD, a stunning decline for a company that was a top performer in the post-COVID years. But despite the drop, the stock still trades at 24 times forward earnings, highlighting the key issue: Trade Desk is still priced as a growth stock, even though its growth has stalled. Revenue grew just 3% YOY to $715 million in the most recent quarter, missing the consensus estimate of $752 million by nearly 5%. Net margins dropped from 13% to 9%, while operating expenses grew 6%. But worst of all, fiscal Q3 2026 guidance calls for just $650 million in revenue, which would represent the first projected YOY sales decline in the firm’s history as a public company. Customer retention remains at 95%, but the revenue decline shows that retained clients are spending less. For a growth stock, that is a far worse sign than losing a few less-committed customers. 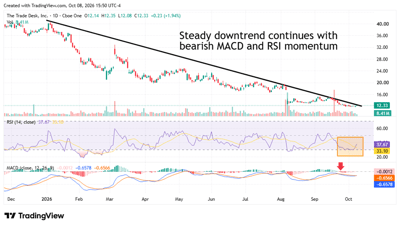
Both the RSI and MACD indicators show strong bearish momentum on the daily chart. The MACD and signal lines remain below zero, while an RSI of 37 reflects significant bearish pressure, though it is not yet in oversold territory. The downtrend should remain strong through the Q4 2026 report on Nov. 5, when the company could potentially update its dismal guidance. Charter: Losses Continue to AccelerateCharter Communications doesn’t offer revenue or earnings guidance, but it does report revenue per user and subscriber growth projections, which give us an idea of where future sales are headed. And as you might have guessed, these figures aren’t heading in the right direction either. Charter lost 172,000 broadband internet customers in fiscal Q2 2026, up from 116,000 lost in Q2 2025. Mobile subscriber growth also slowed to 406,000 line additions, down from 491,000 a year ago. Total revenue beat consensus but fell 1.7% YOY, and the stock hit a 52-week low after the report was released on July 24. The company can absorb subscriber losses if it increases revenue per user, but that figure is also slowing. Charter reported broadband revenue per user of $70.16, down both sequentially and YOY. Losing subscribers and earning less from those who stay is the main reason the stock has seen a wave of analyst downgrades over the last few weeks. The average price target remains $202, representing more than 90% upside from current levels. But this likely means more analyst price target cuts are ahead, not that the stock is undervalued. 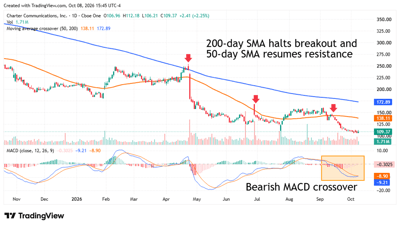
CHTR shares appeared to be stabilizing before the fiscal Q1 2026 report drove the stock down 25% in a single day. The stock had briefly moved above the 200-day moving average for the first time since July 2025, but poor results once again energized bearish momentum. The stock now trades below both the 200-day and 50-day moving averages, with the 50-day average acting as resistance. A bearish MACD crossover confirmed accelerating downward momentum, and Charter will need to show that subscriber attrition is slowing and revenue-per-user metrics are improving before this trend reverses. The company reports its Q3 2026 results on Oct. 30.
(ARReply-675) |

0 Response to "A friendly reminder"
Post a Comment