

I’ll be LIVE at this link in 15 minutes.
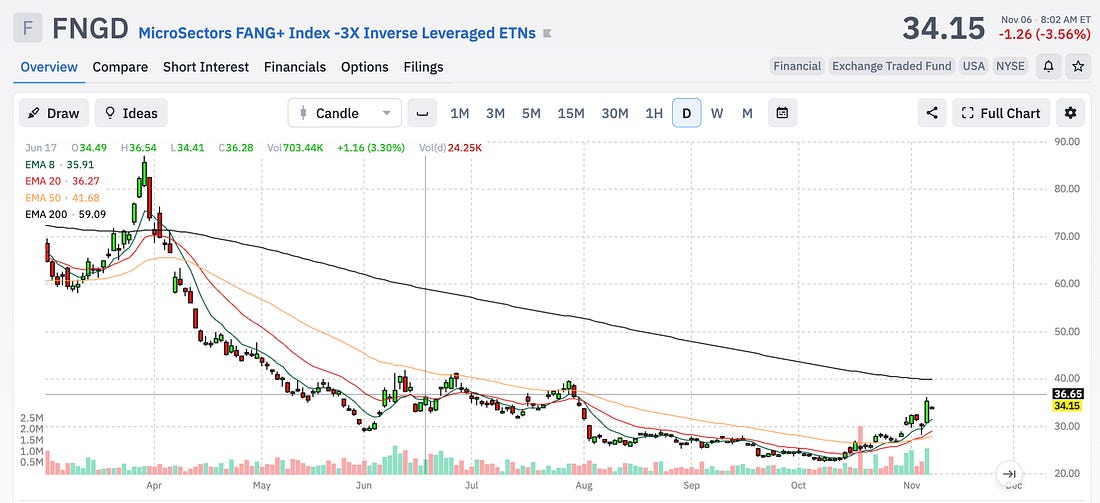
Good morning: So… what happened? Last night, a reader challenged me a bit about markets reacting to political efforts… but I want to stress something. Markets are irrational. Markets are overvalued. And all of the very things that I’ve discussed all came together at once… The mechanical nature of this market and the leverage in it took a massive hit… It showcases the danger of an unwind… and how it all feeds on itself. The question is always what that catalyst is… or what that snowflake is that can suddenly unleash an avalanche. Politics is one thing… and it just needs a push. Yesterday was the worst day for the market since March 2020… a period of real liquidation. The semi index shed more than 12%, and Scott pointed out yesterday in our morning report that investors should fade anything under that 706 level for the Nasdaq 100 (QQQ). I was hoping for a turnaround, but that 200-day moving average was a stop… and as we’ve said repeatedly… nothing good happens when the FNGD is above its 20-day and 50-day moving average.
The question among desks in New York is what this event is… Is this like 1998 when forced selling hit healthy companies and created a buying opportunity? Or is this a structural unwind like 2000? This debate is the entire trade. We’ve been saying for weeks to ask yourself why you own what you own… Well, these are the conditions that make you ask that question. Forced selling creates bargains, but bad economics and tough policy create traps. The mechanics made the situation really bad yesterday… Leveraged ETF rebalancing combined with negative dealer gamma likely amplified the downturn. This is what I’ve discussed about passive flows and how selling builds on other selling automatically. People stop asking what something is worth… and instead hit the sell button because the program tells them to do so… This is not an environment for the reckless… and the question is what conditions need to return for a person to have real confidence. That will likely be a confluence of things… like yields dropping, oil falling, and – perhaps most important – central banks around the globe halting their restrictive policies. The odds of a Fed rate hike in December hit 64%... and a lot of people are questioning if that’s going to happen now. The thing is, the AI trade liquidation is global… This hit Taiwan, Korea, and other places. But investment-grade bonds are getting bids, and we’ve seen Treasuries take in capital for 19 straight weeks. This is classic Phase Four of the liquidity cycle behavior. I’ve said that the AI financing story has taken over the project economics. When you combine the threats of serious regulatory delays with massive amounts of capex figures, you eventually hit a wall. Free cash flow projections on the hyperscalers has gone from positive $191 billion to negative $63 billion this year and negative $252 billion next year. Texas is the real story… as the state has about 30% of the 60+ gigawatts yet to break ground for 2028… Companies have already started looking elsewhere… Not everyone… but just enough to break sentiment. Second look at Brazil? I’m live on payrolls first… Today, we have a consensus of about +65,000 jobs for October with unemployment at 4.2%. Some banks are projecting higher numbers… somewhere in the 75,000 to 80,000 range. A miss would pull down the odds of another rate hike… We’ll go through the report…... Continue reading this post for free in the Substack app
|
||||||||||||||||||||||||||





0 Response to "1998 or 2000? (Live in 15)"
Post a Comment