Good morning -
Today is your second official day as a MarketBeat newsletter subscriber. Welcome! After spending a little time with our website, tools, and newsletters, I think you'll quickly realize we aren't like most financial websites. We aren't pushing specific stocks. We don't play the hype game, and we don't have some agenda we are trying to push on to individual investors.
Our mission is to empower individual investors like you by providing useful research, timely data, and practical tools to help you make better-informed investment decisions.
In this message, I wanted to highlight a few of the tools and resources that our subscribers love and have used for years so that you can make the best use of your MarketBeat subscription. The best place to start is with My MarketBeat, which I'll explain below. Build your watchlist My MarketBeat lets you follow the stocks you already own, along with any companies you’re researching. Once you add a stock, you can quickly see:
- Recent news
- Price performance
- Analyst upgrades and downgrades
- Earnings dates
- Dividend activity
- SEC filings
- Insider transactions
- Additional portfolio ideas
- and much more!
Instead of searching for updates across several websites... You can keep the companies that matter to you organized in one place. Click here to set up your watchlist in My MarketBeat A few other resources worth knowing Once your watchlist is set up, here are a few more ways to use MarketBeat: Daily Analyst Ratings See the latest analyst upgrades, downgrades, and price-target changes from Wall Street research firms. Stock Lists Explore companies by sector, strategy, or investing theme, including dividend stocks, artificial intelligence stocks, and more. MarketBeat TV Watch timely discussions about stocks, sectors, and market developments from the MarketBeat team. You do not need to explore everything today. Start with your watchlist... Add a few stocks you own or follow... And let MarketBeat help you keep track of what happens next. Click Here to Explore My MarketBeat Matthew Paulson
MarketBeat
P.S. If you have any questions about MarketBeat, the tools available to you, or how to find anything at all, just hit reply to this email. Our South Dakota-based support team is here to help.
More Reading from MarketBeat Media
Oil Above $100 Is Creating a New Opportunity Beyond the Major ProducersAuthor: Chris Markoch. Date Posted: 9/12/2026. 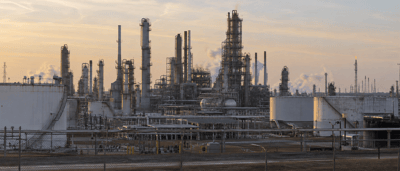
Key Points
- Rising oil prices above $100 per barrel are widening refiners' crack spreads, creating an investment opportunity in Phillips 66, Valero, and Marathon Petroleum.
- All three refiners delivered sharply higher second-quarter earnings, with refining strength helping profits outpace year-ago levels.
- Analyst price targets for all three stocks trail current share prices, suggesting the market is pricing in margin strength faster than Wall Street models.
- Special Report: The company SpaceX cannot operate without
Markets have followed a predictable pattern since the United States-Iran conflict began: When the price of oil rises, stocks fall, and vice versa. On Sept. 10, the price of crude oil crossed the psychologically important $100-per-barrel mark. This comes just before investors receive the latest reading on consumer price inflation (CPI), which is expected to reflect the impact of higher gas prices.
AI spending on data centers, chips and power infrastructure is exploding, and much of it is financed with heavy debt.
Weiss Ratings analyst Nilus Mattive warns that if expected returns fail to materialize, the fallout could hit ordinary Americans' jobs, retirement savings and purchasing power.
He outlines how to prepare for the potential chain reaction in a new briefing. See Nilus Mattive's American AI Apocalypse briefing today
Adding fuel to the sell-off, the CME FedWatch tool puts the odds of an interest rate hike in September at approximately 70%. That has significantly affected technology stocks, which are easy targets for investors seeking liquidity and looking to reduce risk. But money isn’t leaving the market; it’s simply moving to take advantage of higher oil prices. That has benefited integrated oil companies such as ExxonMobil (NYSE: XOM) and Chevron (NYSE: CVX). However, other investors are eyeing the widening crack spread (i.e., the profit margin refiners earn per barrel). That’s creating an opportunity for oil refiners. Phillips 66: The Buyback Signals ConvictionPhillips 66 (NYSE: PSX) fits the widening crack spread thesis particularly well. The company’s integrated refining and midstream footprint means it captures margin on both ends of the barrel. That leverage showed up in its Q2 2026 earnings report. PSX posted earnings per share (EPS) of $9.41, compared with the $7.50 consensus estimate, on revenue of $52.04 billion versus Wall Street’s expectation of $43.60 billion. That’s roughly four times what the company earned in the same quarter a year ago. The analyst forecasts on MarketBeat show that analysts are racing to raise their price targets. Of the 21 firms covering PSX, 15 give it a Buy rating, compared with six Holds. The consensus price target is near $222—about 15% below where shares have recently traded. That gap between the share price and the target reinforces the idea that the market is pricing in margin strength faster than analysts are willing to incorporate it into their targets. The company’s management is also giving the stock a bullish boost. The board authorized a $10 billion stock repurchase program in late July, enough to retire nearly 12% of outstanding shares. Buybacks of that size are typically interpreted as a statement that leadership sees the stock as undervalued relative to where the business is heading. That’s a direct rebuttal to the idea that this rally is driven solely by sentiment. Valero: Institutional Money Is Already ThereValero Energy Corp. (NYSE: VLO) is the purest refining play of the three, with no integrated upstream business to dilute its exposure to the crack spread. That focus is showing up in the numbers: $12.54 in EPS against a $10.11 estimate, with revenue up 48.8% year over year to $44.48 billion. The stock has been the standout performer of the group, trading near its 52-week high and up sharply from its 52-week low of roughly $155. The Valero analyst forecasts on MarketBeat show that 21 brokerages cover VLO, with 10 Buy ratings, including two Strong Buys, compared with eight Holds and a single Sell. That gives the stock a consensus Moderate Buy rating, with an average price target near $301. Like PSX, that price target trails the current share price. What stands out with Valero is its positioning rather than sentiment: Institutional investors own nearly 79% of the float, and several large holders, including a state pension fund, dramatically increased their stakes last quarter. That’s a different signal from retail enthusiasm. It suggests long-term capital is treating the refining-margin story as durable rather than as a short-term spike to be faded. Marathon Petroleum: The Market Has Already VotedMarathon Petroleum (NYSE: MPC) shows perhaps the starkest version of the fundamentals-versus-perception gap. The company reported $17.73 in EPS against a $14.27 estimate, with revenue climbing 53.5% year over year to $51.99 billion. That was one of the strongest beats among oil refiners this earnings season. Seventeen analysts cover MPC, with a consensus Moderate Buy rating based on 12 Buy ratings, four Holds and one Sell rating. But the consensus price target of around $330 sits well below the stock’s recent trading level of nearly $400. Shares have gained more than 140% year to date, outpacing even bullish analyst models. That disconnect, however, is worth watching rather than automatically treating it as an opportunity. Wall Street isn’t broadly bearish on Marathon, but the stock’s fundamentals, driven in part by the same refining-margin strength tied to the oil-price shock, are moving faster than the analyst community can formally underwrite. For investors watching the “perception versus fundamentals” framework play out in real time, that’s the tell. The move in refiner stocks isn’t a story of hype outrunning earnings. It’s about earnings outpacing the models built to price them.
(ARReply-281) |


0 Response to "Your Investing Toolkit"
Post a Comment